

Albert: Budgeting and Banking
Albert - Budgeting & Banking
- 4.5
- 36.97K Reviews
- 5.00M
- Downloads
- Free
- Price
Screenshots
Albert: Budgeting and Banking Pros and Cons
Pros
- User-friendly interface for easy navigation
- No hidden fees or charges
- Real-time alerts for transactions
- Offers cash advance without interest
- Automatic savings feature
Cons
- Limited investment options
- Customer support can be slow
- Requires linking bank accounts
- Cash advance limit is low
- Not available outside the US
 Analysis by All-app
When money decisions affect more than one person, a budgeting app needs to do more than make a screen look tidy. I look for a clear way to understand what is happening, a routine that people can actually keep up with, and sensible boundaries around whose financial details are being handled. Albert: Budgeting and Banking is a finance app from Albert - Budgeting & Banking, and its appeal is the attempt to bring everyday money tasks together. For a household, though, convenience is only useful if everyone understands what the app is—and is not—doing.
Getting Started with Albert
First impressions matter, right? Well, Albert doesn’t disappoint. The app is available for both Android and iOS, and downloading it is a breeze. Once you fire it up, the user interface is clean and intuitive, which is a big win for those of us who aren’t too tech-savvy. You know that feeling when you're navigating something and it just "clicks"? That's exactly what happened here.
Features that Stand Out
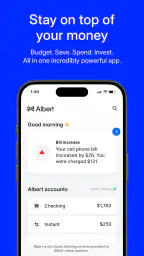
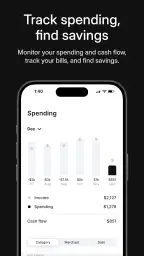
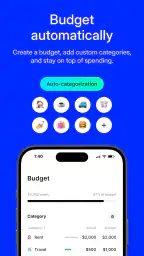
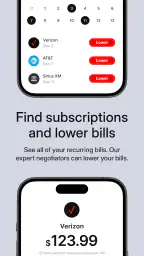
What really caught my attention was Albert’s ability to track expenses effortlessly. The app connects to your bank accounts and does all the heavy lifting, categorizing your spending into neat little sections. It’s like having a personal finance assistant who’s always on call.
But wait, there’s more! Albert also offers savings advice. It analyzes your spending patterns and suggests ways to save money. It’s almost like it's whispering little money-saving secrets in your ear. I found this feature particularly helpful when I was trying to cut down on my coffee shop visits. You know how those lattes add up!
Making a Shared Budget Work Without Sharing a Login
A realistic household use for a tool like this is not necessarily putting every person’s finances into one account. Imagine two adults planning groceries, transport, and a household bill while keeping personal spending separate. One person can use their own financial overview to notice a pattern—perhaps small weekday purchases have crept up—then bring that observation to a conversation about the shared budget. That is a useful role for personal budgeting: it can give the discussion a concrete starting point without turning every purchase into a debate.
I would treat that as coordination by agreement, not as a built-in family workflow. Before anyone connects financial accounts, decide who will use the app, which accounts they are comfortable linking, and what information they want to discuss with the other person. If you need several household members to see a single shared dashboard, assign roles, or jointly approve transactions, check that those specific functions are available before relying on Albert for them. A simple shared note or spreadsheet may be a better companion for household totals when account-level access is not appropriate.
There is also a practical boundary worth keeping: don’t hand over your personal sign-in simply because someone shares your rent or grocery costs. A household budget can be shared without making every bank detail communal. If one person handles the app, they can still agree on a regular summary of shared expenses, while each person keeps control over their own accounts and decisions. That approach is less seamless than a dedicated shared-finance system, but it can be a better fit for couples, roommates, or relatives who want coordination without full financial visibility.
More Reads From Our News Desk

Switching to the Xbox App: What Changes in Your Gaming Routine

Coloring & Learn Review: A Satisfying Canvas, Cluttered Menus

Microsoft 365 Copilot on Your Phone: Who Actually Needs It?

Mafia City: The Crime Saga That Outshines Its Rivals

Woodturning Transformed: How OS Updates Enhance Your Craft

How Tiles Hop EDM Rush Redefines Music Gaming
Setup Boundaries and Day-to-Day Coordination
Albert’s expense tracking is most useful when the underlying account information is relevant to the question you are trying to answer. For a personal spending review, looking at one person’s transactions can be more revealing than mixing them with a partner’s unrelated purchases. For a household review, on the other hand, a combined picture may be useful only if the people involved have chosen that arrangement knowingly. I would start with the smallest setup that can answer the immediate question, rather than connecting everything out of habit.
A small workflow can make the app’s information more actionable. Pick one category you want to understand, review it at a consistent time, and compare what the spending pattern suggests with your actual plans. If the goal is to cut back on coffee-shop visits, for example, decide in advance what a reasonable change looks like. The point is not to treat every suggestion as an instruction; it is to use the pattern as a prompt and then choose a change you can sustain. That keeps budgeting from becoming a cycle of guilt followed by abandoning the plan.
For a household, a short weekly check-in can be more useful than constant commentary. One person might bring up an upcoming shared cost, while the other checks whether the household plan still makes sense. Keep the conversation focused on agreed expenses and goals, not on judging every transaction. Albert can help one user examine their own money habits, but the social part—agreeing on responsibilities, deciding what counts as shared, and changing the plan when circumstances shift—still belongs to the people involved.
That distinction matters if you are wondering whether the app can replace a household budget meeting. I would not use it as a substitute for deciding who pays which bill or how a shared purchase is split. A transaction view can help you understand spending, but it does not automatically settle what feels fair to everyone. For recurring responsibilities, write down the agreement somewhere both people can consult; use the app as an input to that agreement rather than assuming it has created one.
The Genius Behind Albert
Let’s talk about the Genius feature. Imagine having a financial advisor in your pocket. Sounds cool, right? With a subscription, you get access to real human experts who provide personalized advice. It’s like having that friend who’s always great with money to give you a nudge in the right direction.
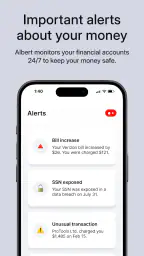
One thing I absolutely love is the alert system. Albert keeps you in the loop with notifications about upcoming bills or when your account balance is running low. It's like having a little reminder buddy in your pocket.
Advice and reminders can be helpful, but I would still make the final call myself. A prompt is a reason to check the situation, not proof that a particular financial choice suits your household. Before acting on advice, consider the real-world details it may not capture: a shared bill that has not cleared yet, a planned expense, or a partner’s separate arrangement. If you use expert guidance, arrive with a specific question and the context needed to explain it. That makes a conversation more useful than asking someone else to take over your decisions.
Alerts also work best as a backstop rather than the whole system. A notification can draw attention to a bill or a balance, but it is still worth keeping your own calendar or bill routine for anything that would cause trouble if missed. If several people share responsibility for a payment, agree on who checks it and who acts; duplicated reminders can create confusion just as easily as forgotten ones. I would use alerts to support a routine, not to assume that another person has seen the same message or will handle the task.
Who It Suits, and What to Compare
Albert is likely to suit someone who wants a single place to look at spending, consider ways to save, and keep an eye on routine money matters. It is also a reasonable starting point for a budgeting beginner who feels overwhelmed by a blank spreadsheet. The app’s average rating is 4.5 from around 142,000 ratings, and it has over 5 million installs. Those figures suggest plenty of people have tried it, but they cannot tell you whether its approach fits your own banking habits or household arrangements.
The alternative is not always another app. A spreadsheet gives you more control over categories and shared totals, but you have to enter and maintain the information yourself. A bank’s own tools may be convenient if you only need to inspect activity in one place, while a dedicated budgeting service may suit someone who wants a more deliberate envelope-style plan or detailed household collaboration. I would compare those options by asking what you need to do every week: observe personal spending, plan a shared budget, or manage several people’s responsibilities. Albert’s broader mix may be appealing for the first task; the other approaches can be clearer when the second or third is the priority.
It may not be the right pick if you prefer to keep financial information entirely offline, dislike connecting accounts to an app, or want fine-grained control over a complex household budget. Likewise, if you only need a basic list of monthly bills, a calendar and a simple spending sheet may involve less setup. I would not choose Albert on the assumption that it automatically coordinates a family or makes financial decisions for you. Its value is greater when you want help seeing patterns and are comfortable reviewing those patterns yourself.
Age, Trust, and Practical Expectations
The app is rated Everyone, and the minimum operating system listed is Android 7.0. The age label is not a substitute for a family conversation about financial privacy. A parent or caregiver considering it for a younger person should first decide what account access is appropriate and whether the young person is ready to interpret spending information responsibly. For an adult sharing a device with relatives, protecting access to financial information is still a personal responsibility; a shared phone does not make a shared account a sensible default.
Albert is free to download, and its current version is 10.0.20. The app was released on January 30, 2019. I would still look carefully at the choices presented during setup and any terms connected with optional services before committing to them. In particular, distinguish between using the app’s core budgeting tools and deciding whether a paid service is worth it. The Genius access described above involves a subscription, so treat that as a separate decision rather than assuming every useful feature comes at no cost.
One question people often have is whether they should link every account immediately. My answer is no: begin only with accounts that are necessary for the job you want the app to do, then see whether the resulting view is useful. Another is whether it can manage shared bills by itself. I would keep responsibility and payment arrangements explicit between the people involved, rather than depending on a personal finance app to coordinate them. And if someone in your home does not want their financial activity visible to another user, respect that boundary; use a separate method to agree on shared totals.
For someone deciding between Albert and a spreadsheet, the trade-off is convenience versus control. Automated categorization can reduce manual upkeep, while a spreadsheet makes it easier to define exactly what a shared category means and who contributes to it. If your spending is simple and you want prompts that help you notice habits, Albert may feel easier to stick with. If your arrangements are intricate, or you need every participant to edit and reconcile the same plan, choose a tool designed around that collaboration—or keep a manual record alongside the app.
Final Thoughts
So, is Albert: Budgeting and Banking worth a shot? I’d say absolutely! It’s user-friendly, packed with useful features, and can genuinely help you get a grip on your finances. Whether you’re a budgeting newbie or a seasoned pro, there’s something here for everyone. The app makes managing money feel less like a chore and more like a game.
If you’re ready to take control of your finances, give Albert a try. Who knows, it might just become your new favorite app!
Until next time, happy budgeting!
My recommendation is strongest for an individual who wants a clearer view of everyday spending and is willing to make their own choices after reviewing the app’s guidance. In a household, I would use it as one person’s budgeting aid and pair it with explicit agreements about shared costs, access, and responsibilities. That combination is more realistic than expecting one app to solve both the arithmetic and the human side of money.
Frequently Asked Questions
What is Albert: Budgeting and Banking?
Albert: Budgeting and Banking is a financial management app that helps users track their spending, set savings goals, and manage their finances more effectively. It integrates budgeting tools with banking features, offering a comprehensive solution for personal finance management. The app is available for both Android and iOS devices, making it accessible to a wide range of users.
How does Albert help in budgeting and saving?
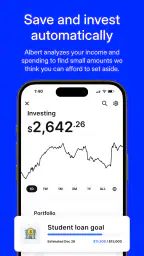
Albert offers a range of budgeting tools that allow users to categorize their expenses, monitor spending habits, and set financial goals. The app automatically tracks spending across various categories and provides insights into areas where users can cut back. Additionally, Albert offers a feature called "Albert Savings," which analyzes your income and spending to find small amounts of money to automatically save, helping users achieve their savings goals effortlessly.
Is Albert: Budgeting and Banking safe to use?
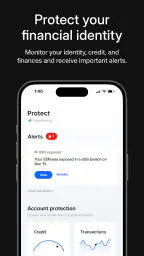
Yes, Albert prioritizes user security by employing bank-level encryption to protect user data. The app does not store sensitive information on your device, and it uses secure servers to manage all transactions. Additionally, Albert offers a multi-factor authentication option to ensure that only you have access to your financial information, providing peace of mind when managing your finances through the app.
Are there any costs associated with using Albert?
Albert is free to download and use, but it offers a premium subscription service called "Albert Genius." This service provides users with access to personal financial advice from experts for a monthly fee. Users can still enjoy many of the app's features without subscribing to the premium service, making it a flexible option for those looking to improve their financial management skills.
Can I link multiple bank accounts to Albert?
Yes, Albert allows users to link multiple bank accounts to provide a comprehensive view of their financial situation. By connecting your accounts, Albert can track your spending across all accounts, offering a complete picture of your finances. This feature is particularly useful for users who manage multiple accounts and want to ensure they are staying on top of their financial goals.


